Liquidating a UAE company involves much more than cancelling its trade licence. A business must settle its financial obligations, close government and employee files, complete tax requirements, and obtain the necessary clearances before the closure is finalised.
For a VAT-registered business, one of the most important steps is VAT Deregistration. If the company has stopped or is stopping its taxable activities, its VAT registration must be reviewed and, where applicable, cancelled with the Federal Tax Authority (FTA).
Why Is VAT Deregistration Important During Company Liquidation?
When a company enters liquidation, it may no longer make taxable supplies. However, simply stopping business activity or allowing a trade licence to expire does not automatically remove the company’s VAT registration.
The FTA requires a separate application through EmaraTax. For a business that is no longer making taxable supplies, the FTA lists documents such as the cancelled trade licence, liquidation letter, board resolution, and latest financial statements among the documents that may be required.
This makes tax closure an important part of the wider company liquidation process in UAE.
Understanding the vat deregistration threshold
Businesses often search for the vat deregistration threshold when their turnover decreases during closure. The UAE’s VAT registration thresholds should not, however, be treated as the only test for deregistration. The circumstances of the business also matter. A company that has ceased making taxable supplies may have a deregistration obligation even when its liquidation is driven by business closure rather than simply falling turnover.
What Is the vat deregistration threshold During Liquidation?
The vat deregistration threshold and the deregistration obligation are two different considerations. During liquidation, the company should establish:
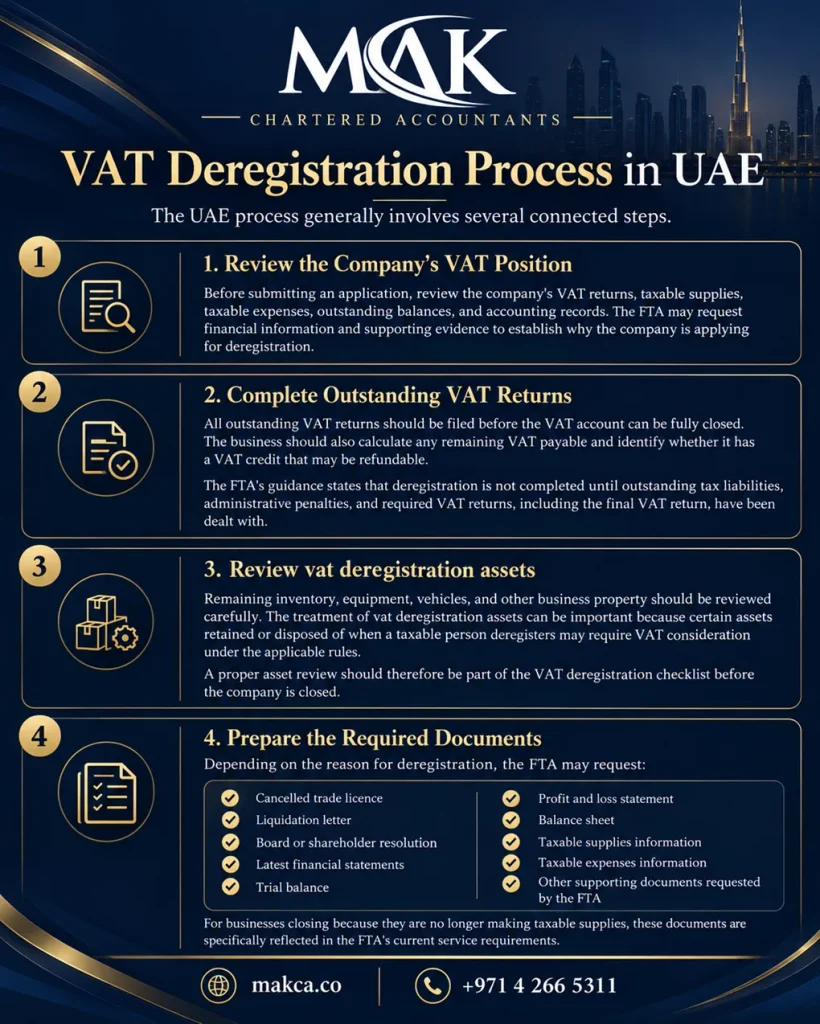
VAT Deregistration Process in UAE
The UAE process generally involves several connected steps.
Review the Company’s VAT Position
Before submitting an application, review the company’s VAT returns, taxable supplies, taxable expenses, outstanding balances, and accounting records. The FTA may request financial information and supporting evidence to establish why the company is applying for deregistration.
Complete Outstanding VAT Returns
All outstanding VAT returns should be filed before the VAT account can be fully closed. The business should also calculate any remaining VAT payable and identify whether it has a VAT credit that may be refundable.
The FTA’s guidance states that deregistration is not completed until outstanding tax liabilities, administrative penalties, and required VAT returns, including the final VAT return, have been dealt with.
Review vat deregistration assets
Remaining inventory, equipment, vehicles, and other business property should be reviewed carefully. The treatment of vat deregistration assets can be important because certain assets retained or disposed of when a taxable person deregisters may require VAT consideration under the applicable rules.
A proper asset review should therefore be part of the VAT deregistration checklist before the company is closed.
Prepare the Required Documents
Depending on the reason for deregistration, the FTA may request:
For businesses closing because they are no longer making taxable supplies, these documents are specifically reflected in the FTA’s current service requirements.
VAT Deregistration Process
Key steps from this article
Completing the vat deregistration form
The vat deregistration form is submitted electronically through the company’s EmaraTax account. The application should clearly explain the reason for deregistration and provide information that matches the company’s financial records and liquidation documentation.
Inaccurate turnover information, inconsistent dates, or incomplete supporting documents can lead to the FTA requesting additional information.
Businesses should therefore ensure the vat deregistration form is reviewed before submission rather than treating it as a simple administrative formality.
Can You Complete vat deregistration online?
Yes. Businesses can complete vat deregistration online through the FTA’s EmaraTax platform. The FTA currently lists the service as available 24 hours a day, seven days a week, with no service fee.
The online process generally involves accessing the taxable person’s account, selecting VAT, choosing the deregistration action, completing the application, and uploading the required documentation. After submission, the application can be monitored through EmaraTax.
What Happens After VAT Deregistration?
Approval does not mean that every tax obligation disappears immediately. The FTA issues a VAT deregistration certificate once the application has been approved. The final tax return must then be submitted and payable VAT settled no later than 28 days from the effective deregistration date.
The final VAT return should cover the company’s last VAT tax period. The business should also retain its VAT records and supporting documentation according to the applicable record-keeping requirements.
vat deregistration assets and Final VAT Treatment
One area that deserves particular attention is the company’s remaining assets. During liquidation, assets may be sold, transferred, distributed, or retained. The VAT consequences should be reviewed based on the nature of the asset and the circumstances of the transaction.
A detailed review can help identify deemed supply VAT, output VAT, and other tax adjustments that may need to be reflected before the VAT account is closed.
Is an hmrc vat deregistration form Relevant to UAE Companies?
No. An hmrc vat deregistration form relates to the UK’s HM Revenue & Customs system, not the UAE Federal Tax Authority.
A UAE company undergoing liquidation should use the FTA’s EmaraTax system for its UAE VAT registration and deregistration requirements. Searching for an hmrc vat deregistration form can therefore lead businesses to the wrong procedure.
Common VAT Deregistration Mistakes During Liquidation
The FTA confirms that incomplete applications can result in requests for additional documentation, which may extend the processing timeline. Businesses can face avoidable complications when they:
How Long Does VAT Deregistration Take?
The FTA currently estimates 20 business days to complete a VAT deregistration application after receiving a completed application. If additional information is requested, the process may take longer.
This is why companies should begin their tax closure work early in the overall UAE company liquidation process.
How MAKCA Helps With Company Liquidation in the UAE?
MAKCA supports businesses with structured company liquidation, including liquidation documentation, audit or liquidation report assistance, liability settlement, visa and labour cancellation, accounting review, and final deregistration support.
Its team can coordinate key closure requirements across tax, accounting, licensing, immigration, and regulatory processes. This can help shareholders complete the liquidation process with organised documentation and fewer compliance gaps.
Conclusion
VAT Deregistration should be treated as an essential part of closing a UAE company, not as a final administrative task after everything else is finished.
From checking the vat deregistration threshold and preparing the vat deregistration form to reviewing vat deregistration assets, filing outstanding returns, and completing the final VAT return, every stage should be handled carefully. For businesses that need vat deregistration online, the FTA’s EmaraTax platform provides the official route.
Frequently Asked Questions
How long does VAT deregistration take during liquidation?
It usually takes around 20 business days for the FTA to process, provided all documents and the final return are correct.
Do I need to file a final VAT return before deregistering?
Yes. The final VAT return must be filed before your deregistration application can be approved.
Can I liquidate my company without deregistering for VAT?
No. VAT deregistration is a required step, and your liquidation certificate can be delayed or refused without it.
Is there a penalty for late VAT deregistration?
Yes. The FTA can issue administrative fines if you deregister after the 20 business day deadline.